AAVE
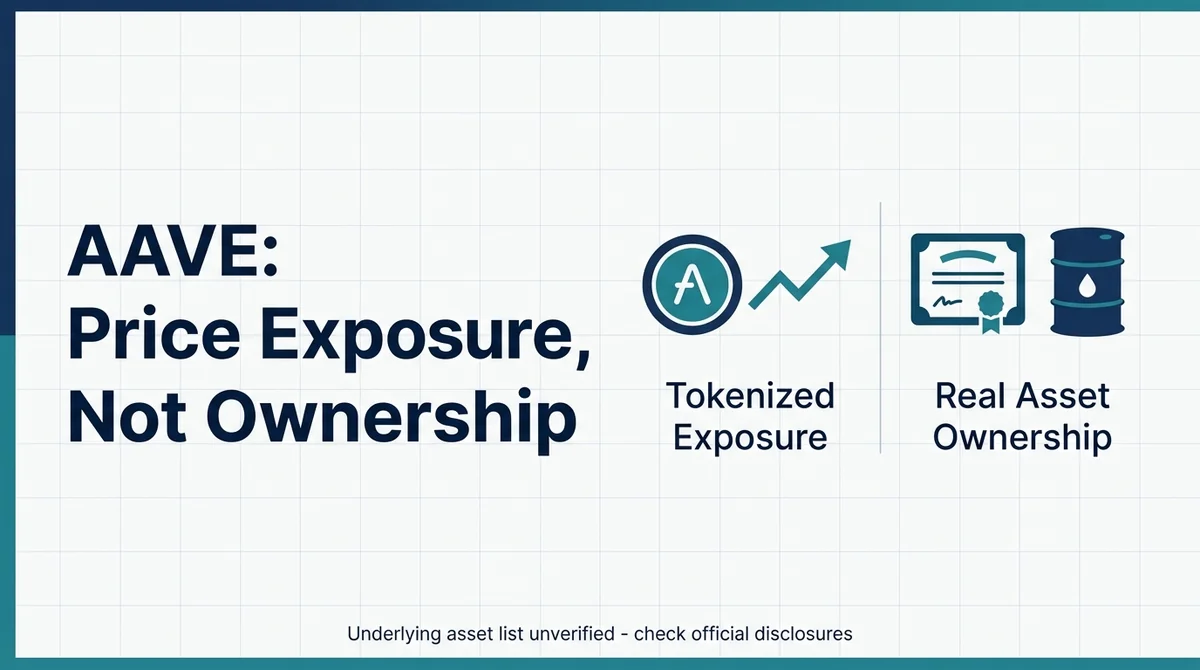
AAVE offers price exposure to security tokens and tokenized commodities, not real ownership. We break down exposure types, coverage, spot vs delivery contracts, and risks.
Conclusion: AAVE provides price exposure to security tokens and tokenized commodities, not ownership of real stocks or physical commodities. It suits users who need multi-market exposure and can accept a non-equity structure, and it is not suitable for users who require genuine shareholder status or specifically need China A-share exposure. The input materials behind this article do not provide an underlying asset list, issuance structure, or fee data; all specific parameters are marked as unverified, so please refer to official disclosures.
#What is AAVE? Does it offer real assets or price exposure?
AAVE offers tokenized price exposure, not real asset ownership. It lets users track the price performance of securities and commodities in token form, but it does not involve holding, voting rights, or delivery of the underlying stocks or physical commodities. The specific underlying asset list and issuance structure are subject to official disclosures.
#What is the relationship between AAVE and real stocks or physical commodities?
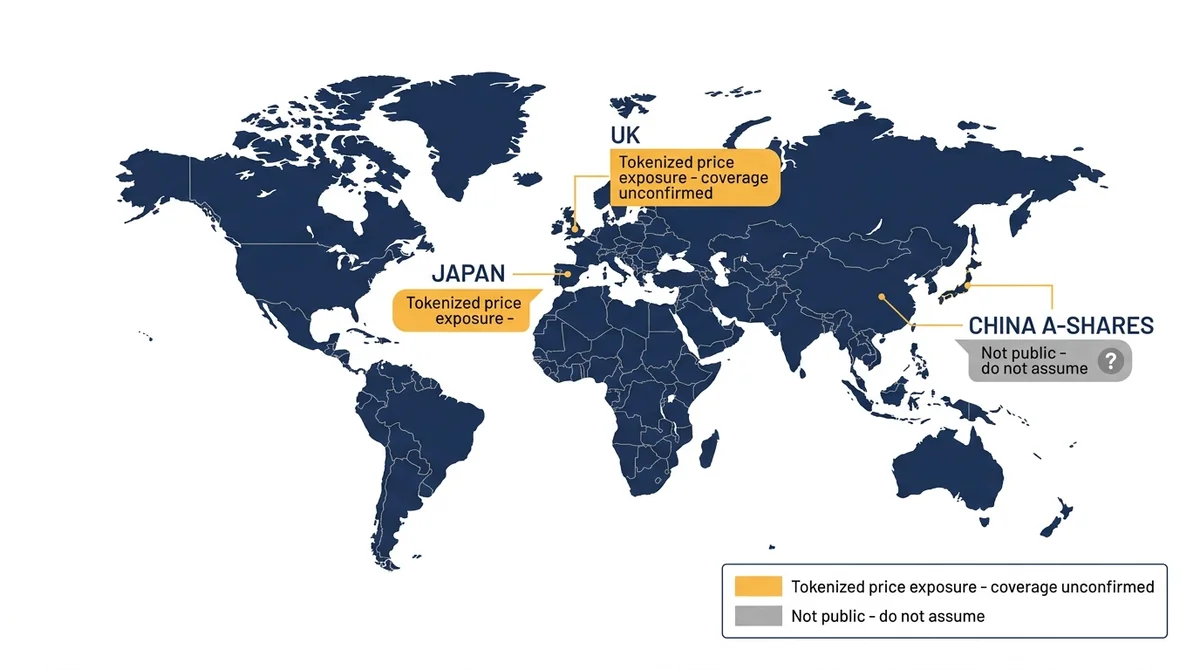
Tokenized stocks are not the same as real US stocks; they only provide price exposure. Holding this kind of exposure generally does not grant shareholder status, voting rights, or direct dividend distributions in the underlying company; the same applies to tokenized commodities, which generally do not involve physical delivery. This is a common industry mechanism for tokenized assets (background knowledge); whether AAVE fully applies it must be confirmed against its official terms.
#What do security tokens and tokenized commodities each mean?
A security token is a carrier that represents the price performance of securities-type assets in token form, with its price anchored to the underlying security's market price; tokenized commodities are carriers that track the prices of commodities such as crude oil and metals in token form. What both have in common is that they provide price exposure rather than asset ownership. These are conceptual definitions and do not amount to item-by-item confirmation of AAVE's specific products.
#Which markets does AAVE's exposure cover?
AAVE's exposure involves markets such as Japanese and UK stocks, but the complete underlying asset list and coverage scope are not confirmed in the input. Before an official list is published, "involves Japanese and UK stocks" should not be read as confirmed full coverage, and other market coverage should not be assumed.
#How should you understand AAVE's Japanese stock, UK stock, and China A-share exposure?
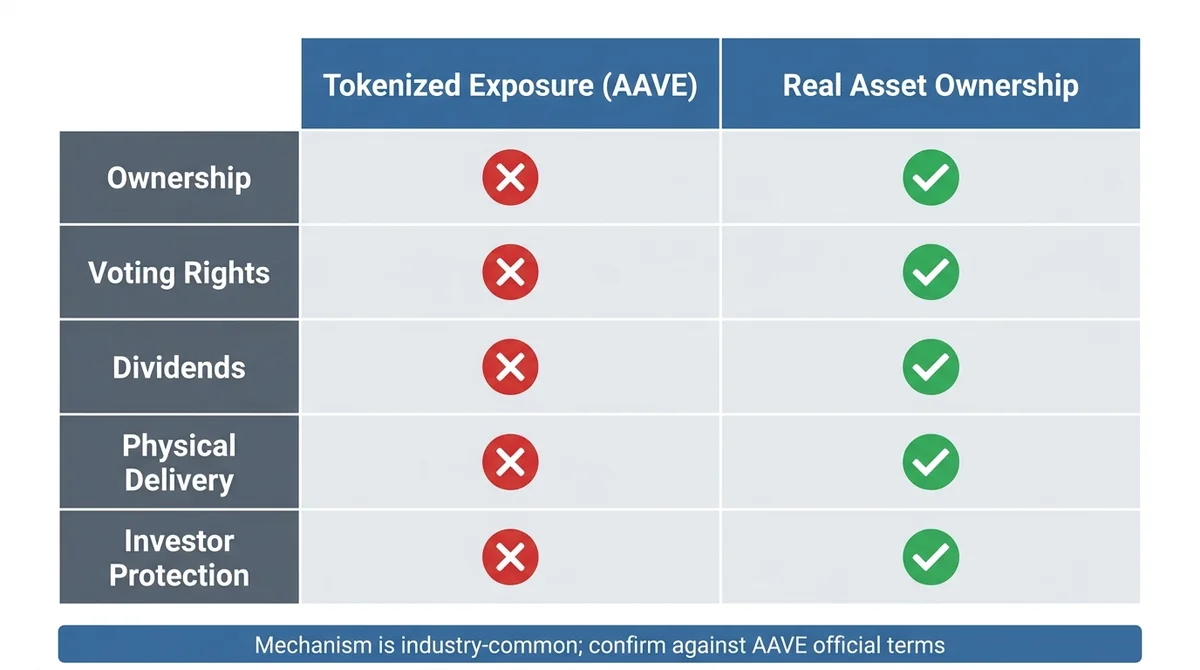
AAVE's Japanese and UK stock exposure is tokenized price exposure, not direct holdings in the local markets; coverage of the China A-share market is not public and should not be assumed. Cross-market allocation must be assessed separately under each market's rules.
#How does AAVE's Japanese and UK stock exposure differ from the real markets?
Japanese and UK stock exposure exists in the form of tokenized price exposure, not direct holdings in the local markets. Prices may follow fluctuations in the underlying markets, but holders do not enjoy shareholder rights in the local markets and are usually not directly covered by local exchange investor protection mechanisms. These differences are common features of tokenized structures (industry-wide mechanisms); whether AAVE fully applies them still depends on its terms.
#Does AAVE cover the China A-share market?
AAVE's coverage of China A-shares is not public, and such coverage should not be assumed. Users who need A-share exposure should rely on the officially disclosed asset list; until that list is confirmed, this dimension is not recommended for A-share allocation comparisons.
#What does cross-market exposure mean for allocation?
Multi-market exposure makes unified management easier, but it does not change the differences in each market's own trading rules. Trading hours, price limit rules, and settlement cycles differ across Japanese, UK, and US markets, and tokenized exposure does not eliminate these structural differences; it may also add issuer-level and platform-level risks.
#How does AAVE's delivery contract differ from spot exposure?
AAVE's delivery contract has an expiry date and perpetual futures leverage, with rollover and liquidation risks; spot exposure has no expiry constraint and suits users who do not need leverage. Specific contract parameters (margin mode, liquidation rules, how does perpetual futures funding rate work) are not given in the input and are marked as unverified.
| Comparison item | Spot exposure | Delivery contract |
|---|---|---|
| Expiry constraint | No expiry date | Has an expiry date; rollover or close-out required |
| Leverage | No leverage | Carries leverage, amplifying gains and losses |
| Liquidation risk | No liquidation mechanism | May trigger liquidation |
| Suitable users | Users who only need price exposure and do not want expiry or liquidation risk | Users who can bear liquidation risk and have the ability to actively manage rollovers |
#What additional risks does the delivery contract's expiry mechanism create?
A delivery contract has an expiry date, so rollover or close-out must be handled. If users do not manage it actively, they may face forced liquidation, and rollover incurs additional costs; the specific magnitude of those costs depends on contract terms and market depth, which the input does not provide and cannot be quantified.
#When should you use spot exposure instead of a delivery contract?
When users only need to hold the price exposure itself and do not need leverage to amplify returns, spot exposure is structurally more suitable, because it has no expiry constraint and will not be forcibly closed at expiry. A delivery contract carries perpetual futures leverage and may be liquidated, so it is only suitable for users who can bear liquidation risk. This is a general judgment based on mechanisms and does not constitute a recommendation of any specific product.
#What are AAVE's five-dimension score and pros and cons?
AAVE's five-dimension score cannot currently be given as comparable specific values; this article only makes qualitative judgments: the strength is diverse exposure types, and the limitation is the structural gap between tokenized exposure and real assets. Data needed for scoring, such as fees, order book depth, and the number of underlying assets, is not public, so this dimension is not recommended for quantitative comparison with other platforms.
#How should coverage breadth, usage threshold, cost transparency, liquidity, and risk control each be assessed?
The five-dimension framework is coverage breadth, usage threshold, cost transparency, liquidity, and risk control. Coverage breadth can be qualitatively described as involving security tokens and tokenized commodities and covering markets such as Japanese and UK stocks (the full scope awaits confirmation in the official list); cost transparency, liquidity, and risk control are not scored because fees, order book depth, and margin rules are not public, and they are not recommended for horizontal comparison; usage threshold can be qualitatively described as requiring an understanding of tokenized structures and delivery contract mechanisms. A "score" without values should not be treated as a comparable review conclusion.
#What are the main strengths and main limitations?
The strength is diverse exposure types, involving security tokens and tokenized commodities and covering markets such as Japanese and UK stocks (coverage scope awaits confirmation in the official list). The limitation is the structural gap between tokenized exposure and real assets, including the absence of shareholder status, no physical delivery, and the information asymmetry caused by the undisclosed underlying asset list.
#Who is AAVE suitable for, and who is it not suitable for?
Users who need multi-market tokenized exposure and can accept a non-equity structure are suitable for evaluating AAVE; users who require real shareholding, specifically need China A-share exposure, or cannot bear leverage and expiry risk are not suitable.
- Suitable: users who need multi-market exposure such as Japanese and UK stocks and accept price exposure rather than shareholding.
- Suitable: users who only need price exposure and want to avoid expiry and liquidation risk by choosing spot exposure.
- Not suitable: users who require genuine shareholder status, voting rights, or direct dividend distributions.
- Not suitable: users who specifically need China A-share exposure and have not waited for confirmation in the official list.
- Not suitable: users who cannot bear leverage, liquidation, and expiry management requirements.
#How should users with Japanese stock, UK stock, or multi-asset exposure needs decide?
The basis for the decision is exposure needs and risk tolerance, not return expectations. If users need multi-market exposure such as Japanese and UK stocks and can accept price exposure rather than shareholding, they can evaluate further; before evaluating, they should first confirm the official asset list and fee structure.
#Why is AAVE not suitable for users who only want to hold real stocks?
Because AAVE provides price exposure and does not involve genuine shareholder status, voting rights, or direct dividend distributions. Users who require real shareholding should choose direct shareholding channels rather than tokenized exposure.
#Where is the boundary for users who can bear leverage and expiry risk?
A delivery contract carries perpetual futures leverage, may be liquidated, and requires active management at expiry. Users who can bear liquidation risk and have the ability to actively manage rollovers may consider a delivery contract; otherwise they should use spot exposure. This boundary is a judgment at the mechanism level; actual risk also depends on margin rules and liquidity, which the input does not provide.
#What risks should you watch for when using AAVE?
The main risks of using AAVE are the structural decoupling between tokenized exposure and real assets, and the liquidation risk brought by delivery contract perpetual futures leverage and the expiry mechanism; there is also information asymmetry risk from the undisclosed underlying asset list.
#Where does the risk of decoupling between tokenized exposure and real assets come from?
Token prices are the effect, and underlying asset prices are the cause. If underlying asset prices fluctuate sharply, token prices will follow, but the tokenized structure itself may produce additional deviation due to factors such as liquidity, issuer credit, and custody fee and redemption mechanisms. The specific sources of these deviations must be based on issuer disclosures, which the input does not provide.
#How do the leverage and expiry risks of delivery contracts amplify losses?
Leverage amplifies gains and losses and may trigger liquidation; expiry delivery requires active management, otherwise forced liquidation occurs. The combination significantly raises the probability and magnitude of losses. The specific liquidation price and margin ratio depend on contract parameters, which the input does not provide and cannot be quantified.
#FAQ
Q1: Is AAVE a real stock? A: No. AAVE provides price exposure to security tokens and tokenized commodities and does not involve genuine shareholder status.
Q2: Does AAVE cover China A-shares? A: This input does not give China A-share coverage; it is marked as undisclosed data, subject to official disclosures, and should not be assumed.
Q3: How do you choose between a delivery contract and spot exposure? A: If you need leverage and can actively manage expiry, you may consider a delivery contract; if you do not need leverage and want to avoid liquidation risk, you should choose spot exposure.
Q4: What is AAVE's five-dimension score? A: The data needed for specific values is not public; this article only provides qualitative analysis, gives no specific score, and does not recommend it for horizontal quantitative comparison.
Q5: Is AAVE suitable for long-term holding? A: It depends on whether the user needs price exposure rather than shareholding. Long-term holding requires attention to the decoupling risk between the tokenized structure and the underlying assets, as well as issuer-level and platform-level credit risk.
Q6: What is the difference between AAVE tokenized stocks and real US stocks? A: The difference is ownership. AAVE tokenized stocks provide price exposure, not real US stock holdings; they do not include shareholder status, voting rights, or direct dividend distributions, and they do not involve physical or stock delivery.
Q7: Does AAVE have China A-share exposure? A: It is currently unconfirmed. China A-share coverage is not public and should not be assumed; the official asset list is the reference.
Q8: How do you choose between perpetual or delivery contracts on tokenized stocks and spot? A: If you only need price exposure, choose spot, with no expiry and no liquidation; only consider delivery-type contracts if you need leverage and can actively manage expiry and liquidation risk.
This content is compiled from public data and does not constitute investment or open account advice. Data is as of 2026-01-01 and may change. To learn about the official asset list and fees, see the official source (commercial link · does not affect scores or rankings).
FAQ
Is AAVE a real stock?
No. According to the input materials, AAVE provides price exposure to security tokens and tokenized commodities and does not involve genuine shareholder status.
Does AAVE cover China A-shares?
This input does not give China A-share coverage; it is marked as undisclosed data, subject to official disclosures, and should not be assumed.
How do you choose between a delivery contract and spot exposure?
If you need leverage and can actively manage expiry, you may consider a delivery contract; if you do not need leverage and want to avoid liquidation risk, you should choose spot exposure.
What is AAVE's five-dimension score?
The data needed for specific values is not public; this article only provides qualitative analysis and gives no specific score.
Is AAVE suitable for long-term holding?
It depends on whether the user needs price exposure rather than shareholding. Long-term holding requires attention to the decoupling risk between the tokenized structure and the underlying assets, as well as issuer-level and platform-level credit risk.
Related Terms
Read the review? Ready to try a small position?
The crypto assets and tokenized US stocks/ETFs covered here are available on MSX — spot and perpetuals.
Quick Start Trading →New here? Registration takes three quick steps.