SpaceX
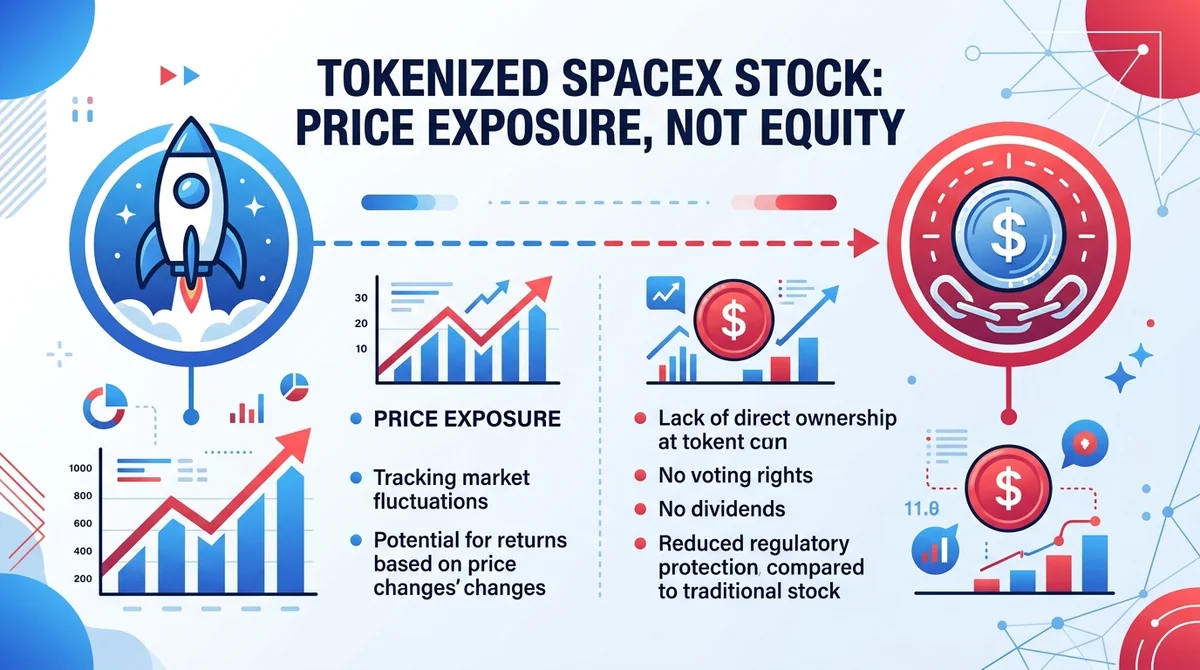
Tokenized SpaceX stock isn't real equity: a five-dimension breakdown of price anchoring, liquidity, issuer custody fee, costs and compliance.
Conclusion: A tokenized stock is a product that issues and transfers a company's stock price exposure on-chain in token form. Holding it usually does not mean holding real equity, and it carries no shareholder rights such as voting rights or dividends. If your goal is only to gain exposure to price movements, you can evaluate it as a structured tool; if your goal is genuine shareholding, it is not suitable. Note that this input provides no verified issuer, fee, liquidity or compliance data for any SpaceX tokenized stock, so all specific figures about such a product are marked "data not disclosed" below; only a judgment framework and a checklist are provided.
#What exactly is a tokenized SpaceX stock?
A tokenized stock is a type of product that issues and transfers a stock's price exposure on-chain in token form. In theory it can be linked to any underlying company, including privately held SpaceX; but whether such a product actually exists, who issues it, and how it is anchored must be based on issuer disclosures. This input provides no relevant product information, so it is data not disclosed. To judge this type of product, the key is not how much the token has risen, but "where the price comes from, who issues it, who holds it in custody, and what the holder actually gets."
#How does it differ from real US stock equity?
Real equity represents an ownership stake in a company, usually carrying voting rights, dividend claims, and eligibility to participate in corporate actions (stock splits, mergers, dividend reinvestment, etc.). Tokenized stocks generally replicate only price performance and do not include these shareholder rights. This input provides no specific rights terms for the product; the relevant terms must be based on the issuer's disclosure documents, and if disclosure is missing, it is treated as data not disclosed.
#Why does the token price follow the underlying stock price?
In this structure, the underlying price is the cause and the token price is the effect: the issuer holds or links the underlying asset so that the token's value references the underlying quote. How closely it tracks depends on the anchoring source, update frequency, and whether the arbitrage mechanism runs smoothly. If secondary-market liquidity is insufficient, the token price may deviate from the underlying quote in the short term, creating a discount or premium. This input provides no anchoring source or update frequency, so it is data not disclosed.
#Does holding the token grant shareholder rights?
Usually not. Tokenized stocks generally do not include shareholder rights such as voting rights or dividends; holders get economic exposure rather than shareholder status. If the product terms provide otherwise (for example, distributing economic returns in another form), the issuer's official documents should govern; this input provides no such terms and marks them as data not disclosed.
Key points of this section: Tokenized stock ≠ real equity, it is only price exposure; the underlying price is the cause and the token price is the effect; it usually excludes shareholder rights such as voting rights and dividends; the issuer and custody structure determine the quality of the exposure.
#How is a tokenized stock different from buying US stocks directly?
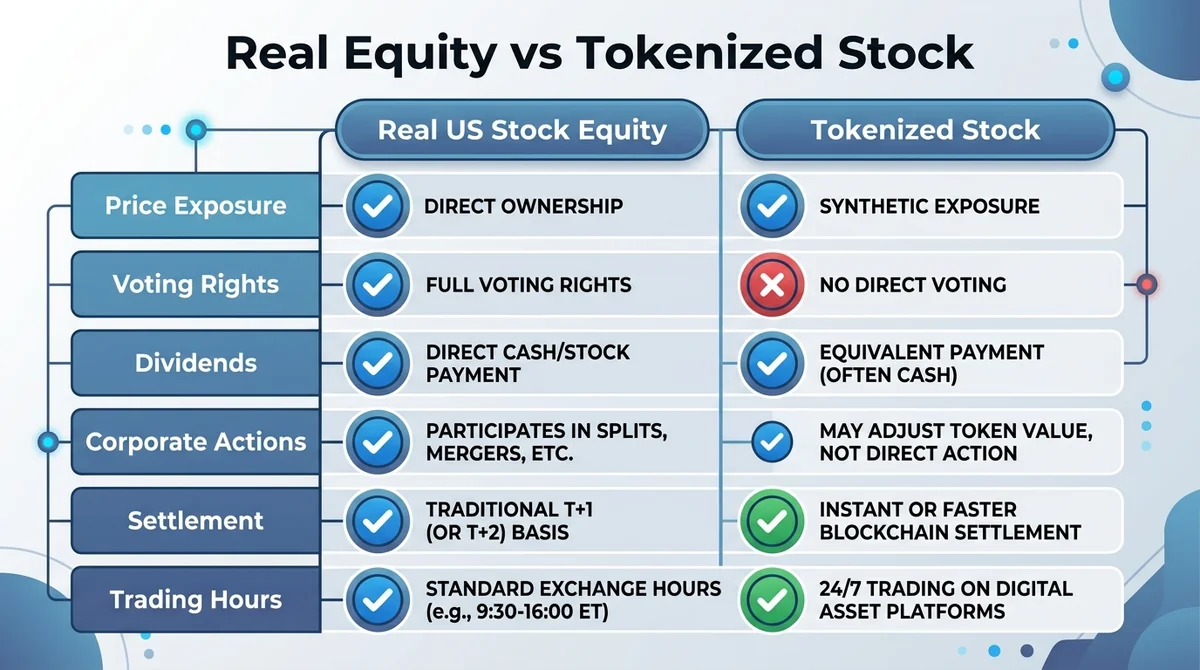
Both may reflect changes in the underlying stock price, but the tokenized version differs from directly holding US stocks in trading hours, settlement method, fee structure, and rights attributes. You need to compare them item by item rather than vaguely asking "which is better."
#Are the price source and anchoring mechanism the same?
When buying US stocks directly, the execution price comes from exchange matching, and price discovery is centralized and transparent; for tokenized products, the price anchoring source, update frequency, and arbitrage path are determined by the issuer's design. The more transparent the anchoring mechanism, the more timely the updates, and the smoother the arbitrage, the smaller the tracking error usually is. This input provides no anchoring details for the product, so it is data not disclosed; it is advisable to check the issuer's disclosures directly.
#What are the differences in trading hours and settlement?
On-chain tokens can usually be traded 24/7, with settlement completed on-chain and speed depending on the network used; US stocks are matched during regular trading hours, and settlement follows local market rules. Longer trading hours do not mean better liquidity—depth is often thinner and spreads may be wider outside US stock hours.
#How do holding costs and fee structures compare?
The cost of directly holding US stocks usually includes commissions, currency conversion costs, and possible account fees; the cost of tokenized products may include trading fees, issuance or custody fee, and funding costs for leveraged structures. Because this input provides no fee data for the product, all cost items are marked as data not disclosed, and no quantitative comparison can be given; only a checklist can be provided (see the action checklist below).
Key points of this section: The price anchoring source and update frequency, trading sessions (on-chain 24/7 vs. US regular hours), fee structure (trading fees, issuance/custody fee, funding costs), and liquidity and bid-ask spread are four differences that must be checked one by one; missing items are uniformly marked as data not disclosed.
#What five dimensions should you use to evaluate a tokenized stock?
Evaluation should score five dimensions item by item—price anchoring, liquidity, issuer credit, holding costs, and compliance—rather than looking only at price gains. Below are the observable indicators and judgment criteria for each dimension; because this input provides no specific data for the product, no numerical score is given for any dimension, and all are marked as data not disclosed.
#Is price anchoring reliable?
Observable indicators: underlying asset, price update frequency, historical tracking error, deviation magnitude under extreme market conditions. Judgment criteria: the anchoring source is verifiable, the update frequency is clear, and tracking error is within an acceptable range. Current status: data not disclosed.
#Are liquidity and spreads acceptable?
Observable indicators: average daily trading volume, order book depth, bid-ask spread, slippage on large trades. Judgment criteria: at the planned trade size, slippage and spreads will not significantly erode expected returns. Current status: data not disclosed.
#How do you judge issuer and custody risk?
Observable indicators: the issuer entity and qualifications, the custody arrangement for the underlying asset, whether reserves or audits are disclosed, and the redemption mechanism. Judgment criteria: the structure is verifiable, the custody arrangement is clear, and there is an executable redemption path. Current status: data not disclosed.
#Will holding costs erode returns?
Observable indicators: trading fees, issuance or custody fee, funding costs, cross-chain or deposit/withdrawal costs. Judgment criteria: convert one-way and round-trip costs into percentages and compare them with the expected holding period and volatility. Current status: data not disclosed.
#What is the regulatory and compliance status?
Observable indicators: which jurisdictions the product serves, whether the relevant licenses have been obtained, and local regulators' stance on tokenized stocks. Judgment criteria: whether your own region is within the service scope and whether the relevant stance is stable. Current status: data not disclosed.
Key points of this section: The five-dimension scoring framework is price anchoring, liquidity, issuer credit, costs, and compliance; each dimension has observable indicators and judgment criteria; missing data are uniformly marked as data not disclosed; no stock-picking-style total score is given, only dimension conclusions.
#Who is a tokenized stock suitable for, and who is it not suitable for?
Suitable for: People who need exposure to the underlying stock price but face regional or account constraints that make direct participation in US stocks difficult, and who understand the structural risks of tokenization (issuer, custody, liquidity, regulation).
Not suitable for: People who require real equity, dividends, and voting rights; people who cannot tolerate discount/premium and liquidity risk; and people who treat tokenized stocks as a "risk-free substitute."
Position size and risk budget should come before judging the underlying: first determine this exposure's proportion of total assets and the tolerable drawdown, then decide whether to use the tool.
#Scenario routing
- If you want price exposure but cannot buy US stocks directly**, then** first check the issuer's qualifications, custody arrangement, and redemption path, then evaluate spreads and costs.
- If you seek real shareholding and shareholder rights**, then** this tool is not suitable for you, and you should turn to a direct shareholding path.
- If you can tolerate derivatives risk and want to amplify exposure**, then** first clarify perpetual futures leverage and funding costs, and position it as a tactical position rather than a core holding.
- If you aim for long-term holding**, then** focus on checking holding costs and tracking error, because the longer the time, the greater the cumulative impact of costs and deviation.
- If you are in a region with an unclear regulatory stance**, then** first confirm service availability, then discuss price and fees.
#Action checklist
- Review the issuer's disclosure documents to confirm the underlying, anchoring source, and update frequency.
- Confirm the custody arrangement: who holds the underlying asset and whether reserves or audits are disclosed.
- Check the redemption mechanism: whether redemption is possible, and the conditions and timing.
- Test the order book: estimate spreads and slippage at the planned trade size.
- Sum up all fees and convert them into one-way and round-trip cost percentages.
- Confirm whether your region is within the service scope and what the local regulatory stance is.
- Set position limits and stop-loss rules before executing trades.
#Risk history
This input provides no historical risk event records for the product (such as de-pegging, suspended redemptions, or liquidity events), and the relevant situation is marked as data not disclosed. General risk types for reference include: issuer credit risk, custody arrangement risk, discount/premium risk caused by insufficient liquidity, risk of changes in regulatory stance, and the risk of short-term decoupling between the token price and the underlying stock price.
#FAQ
Is a tokenized stock a real stock? No. It provides price exposure and usually does not include shareholder rights such as voting rights and dividends; holding it does not make you a shareholder.
Is the token price always equal to the underlying stock price? Not necessarily. The anchoring mechanism and liquidity determine tracking quality; when liquidity is insufficient, short-term discounts or premiums may appear.
It can trade 24 hours a day—is that better? Longer trading hours only mean a wider window in which you can trade; they do not mean better liquidity. Order book depth is often thinner outside US stock hours.
How do you judge whether the issuer is reliable? Look at the entity's qualifications, custody arrangement, reserve or audit disclosures, and whether the redemption mechanism is clear and executable. This input provides no relevant data.
What should you look at first when evaluating this type of product? First check whether price anchoring is reliable and whether the redemption path is executable, then look at liquidity and costs, and finally at compliance and service scope.
This content is compiled from public data and does not constitute investment or open account advice. Data is as of 2026-01-01, and actual conditions may change. To learn about specific terms and the latest data, check the official sources of the issuer and trading platform.
FAQ
Is a tokenized stock a real stock?
No. It provides price exposure and usually does not include shareholder rights such as voting rights and dividends; holding it does not make you a shareholder.
Is the token price always equal to the underlying stock price?
Not necessarily. The anchoring mechanism and liquidity determine tracking quality; when liquidity is insufficient, short-term discounts or premiums may appear.
It can trade 24 hours a day—is that better?
Longer trading hours only mean a wider window in which you can trade; they do not mean better liquidity. Order book depth is often thinner outside US stock hours.
How do you judge whether the issuer is reliable?
Look at the entity's qualifications, custody arrangement, reserve or audit disclosures, and whether the redemption mechanism is clear and executable. This input provides no relevant data.
What should you look at first when evaluating this type of product?
First check whether price anchoring is reliable and whether the redemption path is executable, then look at liquidity and costs, and finally at compliance and service scope.
Read the review? Ready to try a small position?
The crypto assets and tokenized US stocks/ETFs covered here are available on MSX — spot and perpetuals.
Quick Start Trading →New here? Registration takes three quick steps.